
You can finance a pinball machine in three main ways: a pay-over-time plan at checkout (a buy now, pay later or installment loan), a personal loan or credit card, or, if the machine is for a business, equipment financing or a lease. Which one is cheapest depends on the promotional period, your credit and whether the machine is for your game room or your venue. This guide walks through each route, what the numbers look like, and how to avoid borrowing more than a machine is worth to you.
TL;DR
- Home buyers usually finance at checkout through an installment provider. Affirm advertises APRs from 0.00% to 36.00%, terms of 3 to 48 months and purchases up to $30,000, so your rate depends on your credit profile.
- Business buyers can use equipment financing (you own the machine) or a lease (lower upfront cost, easier to rotate titles). Equipment terms generally run 24 to 60 months.
- Used machines, and several machines bought together, can usually be financed too, depending on the lender.
- Compare total cost, not just the monthly payment. A longer term lowers the payment and raises the interest you pay.
- Trade in or sell a machine you already own to shrink the amount you need to borrow.
Table of Contents
- The main ways to finance a pinball machine
- How the cost of financing works
- Financing used machines, preorders and multiple machines
- Does Stern finance pinball machines?
- Is financing a pinball machine a good investment?
- Business owners: tax and ownership points
- How to keep your payment manageable
- Shop new and used machines with nationwide delivery
- FAQ
- Sources
The main ways to finance a pinball machine
A new pinball machine is a real purchase. Crestmont Capital’s guide puts new commercial machines from makers such as Stern, Jersey Jack and American Pinball at roughly $6,500 to $19,000, and used or reconditioned ones at $2,500 to $6,000. Most people do not want to drop that in one go, so here is how the options compare.
| Option | Best for | Typical term | What to watch |
|---|---|---|---|
| Checkout installment plan (BNPL) | Home buyers wanting a quick decision | 3 to 48 months | Promo 0% periods can be short; rate depends on credit |
| Personal loan | Buyers who want one fixed payment | Set by the lender | Origination fees and rate vary by credit |
| Credit card | Smaller purchases, accessories | Revolving | High ongoing APR if not paid off during any intro period |
| Equipment financing | Businesses that will keep machines | 24 to 60 months | You need business and credit history |
| Equipment lease | Operators who rotate titles | Set in the agreement | You may not own the machine at the end |
| Saving or trade-in credit | Anyone | None | Slower, but no interest |
Checkout installment plans
This is the route most hobbyists take, and it works like buying a sofa. You pick the machine, choose a pay-over-time option at checkout and get a decision in minutes. Providers in this space include Affirm, Bread Pay and PayPal Pay Later.
Two structures are common. Bread Pay, for example, offers Split Pay, four interest-free payments billed every two weeks, and longer installment loans, typically 6 to 48 months, which may carry interest depending on the retailer and your creditworthiness. Four payments over about six weeks is fine for an accessory or a cabinet upgrade. For a machine, you will almost always be looking at the longer installment loan.
The same review points out that terms vary a lot from one merchant to the next. That is the reason to read the specific offer on your screen: the APR, the length and the total repaid, before you click confirm.
Personal loans and credit cards
If you would rather borrow outside the checkout, a personal loan from a bank or credit union gives you one fixed payment and a clear end date. A card with an introductory 0% period can work if you are certain you will clear the balance before the promotion ends. If you are not, the standard card rate will usually cost more than a fixed installment loan, so run the numbers first.
Equipment financing and leasing for businesses
If the machine goes into a bar, arcade, restaurant or entertainment venue, business financing opens up. Businesses can finance pinball machines through equipment financing, equipment leasing or a business line of credit. The machine itself typically serves as collateral, which often makes approval simpler than an unsecured loan.
The core difference is ownership:
- Equipment financing: you borrow the price and own the machine from day one. It suits operators who plan to keep machines for years and build equity.
- Equipment leasing: you pay to use the machine, with options at the end that can include buying it, renewing or upgrading. It can lower the upfront cost and suits operators who like to refresh the floor with newer titles.
Lenders generally look at time in business, personal and business credit, and recent bank statements showing cash flow, and many can approve and fund within 24 to 72 hours once paperwork is in. A startup with no history can still look into financing, but expect a down payment or a higher rate.
How the cost of financing works
Three numbers decide what you really pay: the APR, the term and any promotional period.
APR is the yearly cost of borrowing. A 0% offer costs nothing extra if you pay on schedule, while a 25% or 30% APR adds a lot over several years.
Term is how long you take to repay. Shorter equipment terms mean higher monthly payments but less total interest, and longer terms lower the payment but stretch the cost over more months.
Promotional periods (such as 0% for 6 or 12 months) are fine when you can clear the balance inside the window. Check what happens if you cannot: some plans charge interest from the start date, others only from the end of the promotion.
A worked example
Say you are buying a machine priced at $8,000. These figures are an illustration of the arithmetic, not an offer from any lender.
| Scenario | Monthly payment | Total repaid |
|---|---|---|
| 0% for 12 months | $666.67 | $8,000 |
| 12% APR over 24 months | about $377 | about $9,050 |
| 22% APR over 24 months | about $415 | about $9,960 |
| 22% APR over 48 months | about $251 | about $12,050 |
The 48-month plan feels cheapest every month and ends up costing the most overall. If a lower payment is what makes the purchase possible, take the longer term, but pick a plan that lets you pay early with no penalty so you can shorten it later.
Fees and fine print
Before you accept any plan, find these five things:
- The APR, shown as a range or a single figure for your approval.
- Whether interest is deferred or simply waived during a promo window.
- Late fees. Some providers charge none, Affirm among them according to LendingTree’s comparison, while others do.
- Prepayment rules.
- Whether delivery, tax and accessories are included in the financed amount.
Financing used machines, preorders and multiple machines
Used and reconditioned machines can be financed, and a single bundled agreement can cover several machines bought together. For a collector or an operator filling a room, one agreement is easier to track than several small ones.
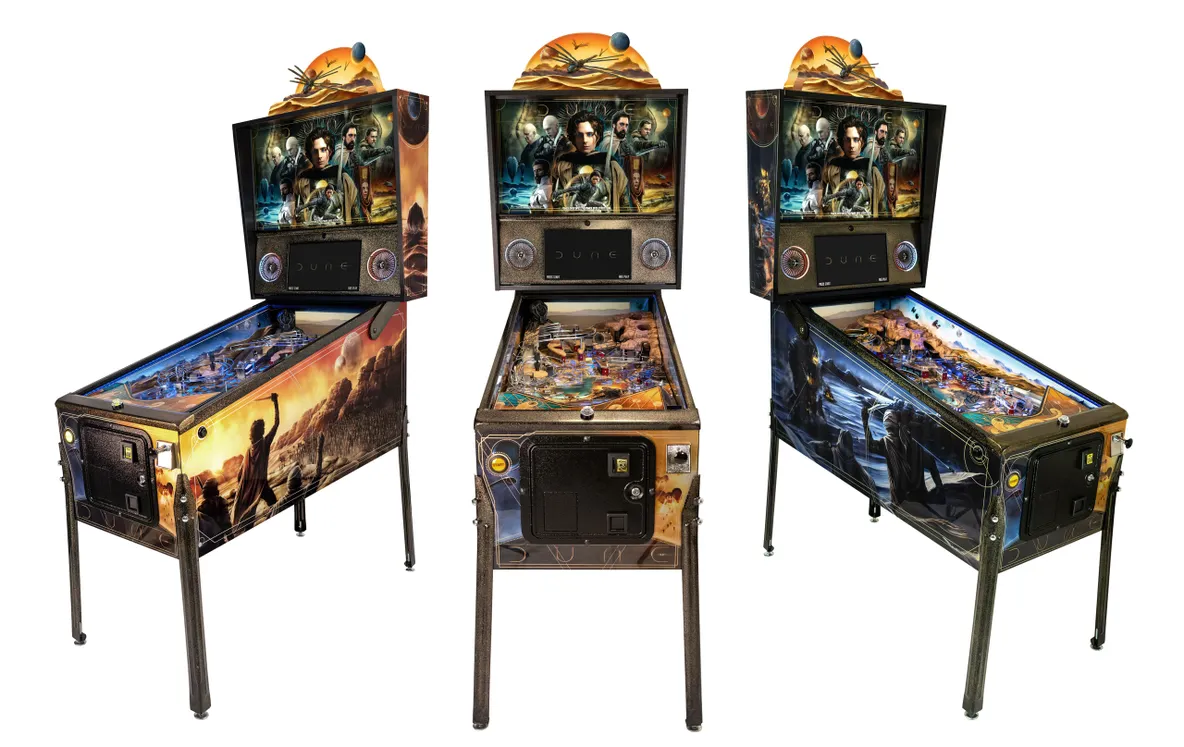
Preorders are a different matter. Many preorders take a deposit first and the balance later, and whether a lender will finance before the machine ships varies by provider. Look at the payment terms on the product page, like our Dune preorder from Barrels of Fun, which is deposit only, and plan how you will pay the balance before it arrives.
Does Stern finance pinball machines?
Buyers generally do not borrow from the manufacturer. Machines are sold through authorized dealers, and financing is arranged by the seller or a third-party lender. Stern’s own Find a Dealer page shows this: it lists dealers and notes which of them have financing available. When you shop, ask the seller directly which payment methods they take and read the lender’s terms yourself.
Is financing a pinball machine a good investment?
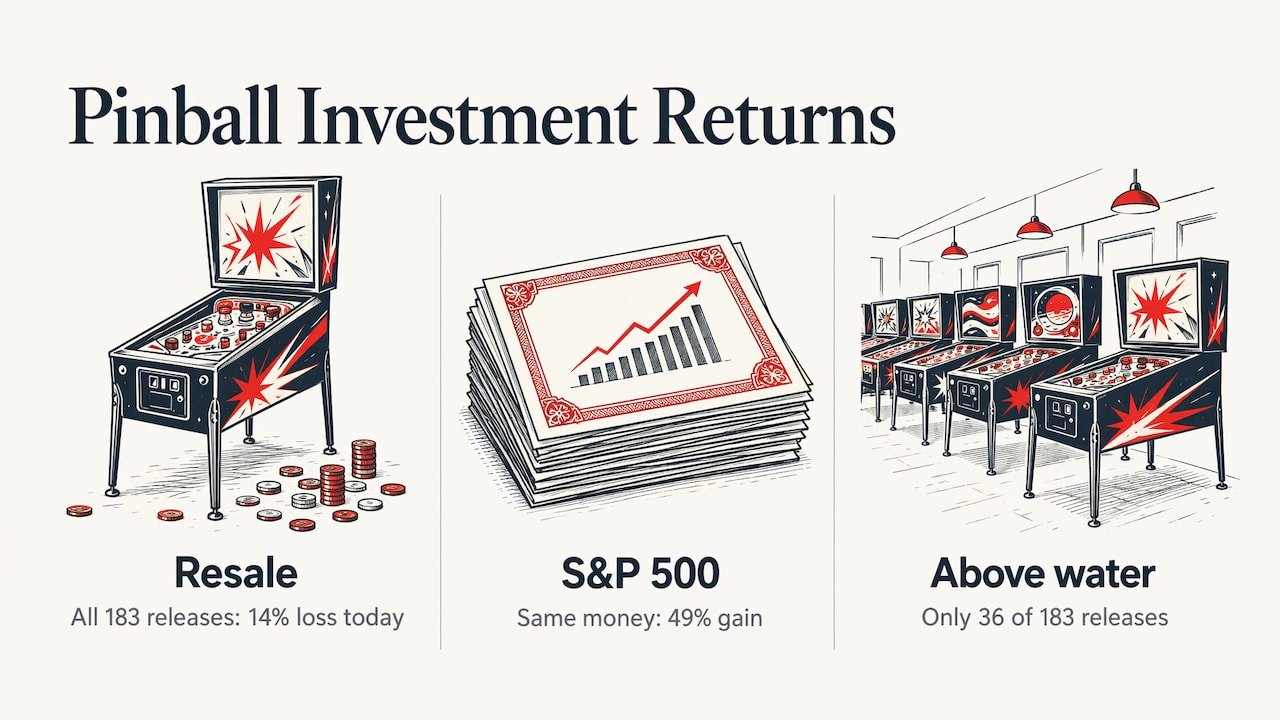
Buy a machine because you want to play it, not because you expect it to pay you back. Collector-grade resale values exist, but the broad market is not a guaranteed gain. Colin Alsheimer’s analysis for Kineticist looked at 183 modern releases and trims since 2017 and found that buying all of them and selling today would produce a 14% loss, while the same money in an S&P 500 index fund would be up 49%. Only 36 of the releases were above water.
What that tells a financing buyer is practical: if interest adds to the cost, the machine has to earn its place through play, atmosphere or, for a venue, revenue. Choosing a title you will enjoy for years, and keeping the loan short enough that you are not underwater when you want to sell or trade, is the sensible approach.
Business owners: tax and ownership points
If you buy for a business, tax treatment matters as much as the rate. Section 179 of the Internal Revenue Code lets a taxpayer elect to expense the cost, or part of the cost, of qualifying property in the year it is placed in service, and the regulations also cover lessors treated as owners for federal tax purposes. Whether a given machine and agreement qualify depends on your facts, including business use and how the lease is structured, so go through it with your CPA before you sign.
Also check your local rules. Pinball machines count as coin-operated amusements, and many states and cities require licenses or permits for placing them in public venues. Your city or state licensing office can tell you what applies.
How to keep your payment manageable
- Set the budget first. Decide the monthly amount that fits comfortably, then choose the machine.
- Use trade-in value. If you already own a machine, selling or trading it reduces what you finance. Our buy, sell and trade service exists for exactly this.
- Add a down payment. Even 10 to 20 percent lowers interest across the whole term.
- Count the extras. Shipping, leveling, a topper, protectors and art blades add up. Our guide to pinball machine shipping cost helps you plan that line.
- Pick a title you will keep playing. Themes you love hold your attention longer than hype does.
- Choose a plan with no prepayment penalty so a bonus or tax refund can shorten the loan.
Our view on paying for a machine
We have sold pinball long enough to know that the best purchase is the one a buyer is still happy with years later. We are an authorized dealer for brands including Stern Pinball and Spooky Pinball, so you get access to new releases and exclusive offers through us, and our used inventory gives you another way to get into the hobby at a lower price point.
Our advice is to plan the whole cost before you fall for a title: the machine, delivery, accessories and how you will pay. We also take Bitcoin and other cryptocurrency, which suits buyers who prefer to pay with digital assets they already hold and want to avoid borrowing altogether.
If you have a machine you are ready to move on from, our buy, sell and trade service can put that value toward your next one.
the author
Shop new and used machines with nationwide delivery
We sell new and used pinball machines from major brands, plus official accessories such as toppers, art blades and parts. We deliver across the lower 48 states, and we accept Bitcoin and cryptocurrency. Start with our pinball machines, see our Stern lineup, or check what is available now on the current inventory list.
Not sure which brand suits you? Our guide to the best pinball brands in the USA explains how the major makers differ, and the Iron Maiden Premium and Jaws Premium pages show what a modern premium machine looks like.
FAQ
Can I finance a pinball machine with bad credit?
Sometimes, but expect a higher APR or a smaller approved amount. Installment providers set rates by credit profile, and Affirm’s published range runs from 0.00% to 36.00%. A down payment, a lower-priced used machine or saving a bit longer all reduce the risk of an expensive loan.
Does Stern finance pinball machines?
Stern sells through authorized dealers, and financing comes from the dealer or a lender they use. Stern’s dealer locator marks dealers that have financing available. Ask the seller about payment options before you order.
Is it better to lease or finance a pinball machine for a business?
Financing suits operators who want to own machines and build equity. Leasing can lower the upfront cost and suits operators who like to swap in newer titles, according to Crestmont Capital’s guide. Your accountant can confirm which fits your tax situation.
How long does financing approval take?
Checkout installment plans typically give a decision in minutes. For business equipment financing, many lenders approve and fund within 24 to 72 hours once documents are in hand. Have your bank statements and business details ready.
Can I avoid financing altogether?
Yes. You can save toward the machine, sell or trade a machine you already own, or pay with cryptocurrency, which we accept. A used machine from our inventory is another way to start at a lower price.
Sources
- Best Buy Now, Pay Later Sites & Apps, LendingTree
- Pinball Machine Financing: The Complete Guide for Business Owners, Crestmont Capital
- How Good is Bread Pay? Review and BNPL Comparison, Gerald
- Find a Dealer, Stern Pinball
- Pinball Investments, Kineticist
- 26 CFR 1.179-1, Election to expense certain depreciable assets
- Chapter 13: Coin Operated Amusements